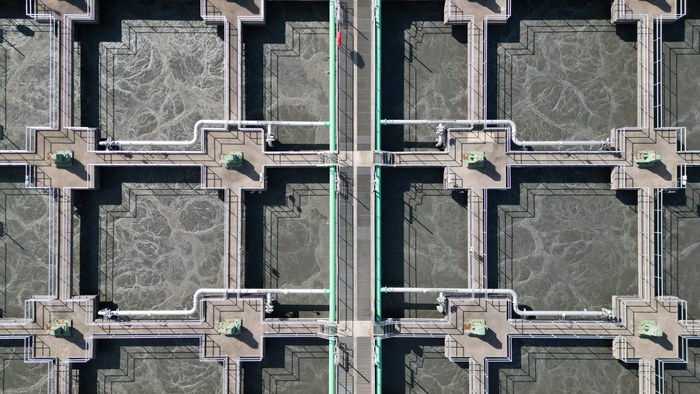
ACWA Power has signed a water purchase agreement with the Dubai Electricity and Water Authority for the Hassyan seawater reverse osmosis independent water project, the Saudi utility developer told the Saudi Exchange on 28 October 2026. The plant, in the Hassyan complex in Dubai, is designed for a daily production capacity of about 272,000 cubic metres of desalinated water.
The filing puts the contract value at 478 million dollars, equivalent to 1,794 million Saudi riyals, over a term of 30 years. ACWA Power will hold a 40 per cent share of the project and the scope covers development, financing, construction and operation of the plant. The company told the exchange that the financial impact is expected to begin once the project is successfully completed, which it puts at 2030. The issuer recorded the award and the signing on the same day, so there is no gap here between the announcement date and the contract date, which is not always the case with Gulf infrastructure disclosures.
The agreement is the second substantial ACWA Power disclosure inside a month. Earlier in October the company reported financial close on the Rabigh 2 independent power producer expansion in Saudi Arabia, and in late September it declared the start of initial commercial operation at the Qassim 1 combined cycle plant. Read together, the three filings describe a developer converting a pipeline into contracted, revenue bearing assets rather than announcing new ambitions.
Two things are worth drawing out. The first is the geography. ACWA Power is a Saudi listed company whose identity is bound up with the kingdom's own water and power build out, and this contract is in the United Arab Emirates with the Dubai utility as offtaker. A 30 year water purchase agreement with a sovereign linked counterparty in a neighbouring market is a different proposition from a domestic award: it diversifies the regulatory and counterparty exposure that has concentrated in Saudi Arabia, and it does so in the one Gulf market with comparable desalination demand. The 40 per cent share also signals that this is a consortium position rather than a lead developer role, which caps both the capital at risk and the upside.
The second is the shape of the economics. The headline contract value is large but the stated financial impact does not arrive until the end of the decade, which is the standard profile for a build own operate water project and is worth stating plainly because a contract value is not revenue and is not earnings. What a water purchase agreement of this length actually supplies is a long dated, inflation linked, availability based cash flow, and the value of that depends far more on the financing terms reached before construction than on the headline number disclosed today. The useful thing to watch is therefore the financial close, not this signing.