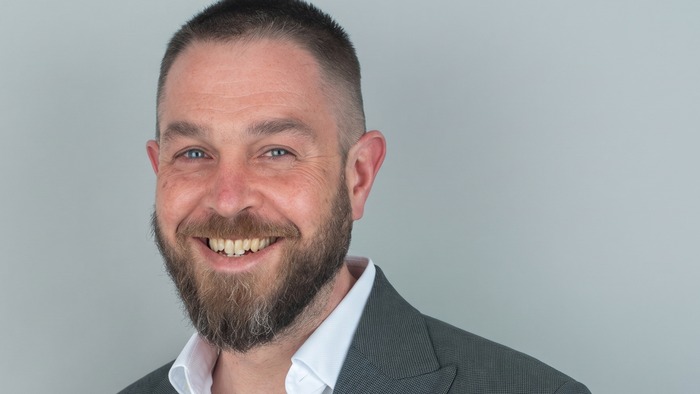
Marimaca Copper has promoted Peter Garner-Winship to Chief Financial Officer with immediate effect, elevating its vice president of finance as the Chilean copper developer moves from study work towards construction financing.
He joined the company from Anglo American, where he spent seventeen years across corporate finance, strategic planning and capital allocation. The most directly relevant part of that record is his period as Financial Controller of the Quellaveco copper project in Peru, one of the largest greenfield copper builds of the past decade.
That experience is the reason the appointment reads as deliberate rather than routine. Marimaca is advancing an oxide copper deposit in Chile's Antofagasta region, and a company at that stage faces a specific and unforgiving finance problem: it must raise construction capital against a technical study rather than against production, while holding a capital cost estimate that the market will test line by line. A finance chief who has controlled the books of a project actually in construction has seen where those estimates move and why.
Promoting from within also preserves continuity at a point in a project's life when continuity has unusual value. The financial model, the assumptions behind it and the relationships with the banks and offtakers that will fund the build are largely carried in the heads of the people who built them, and a company that changes finance chiefs during a financing process typically pays for that in time.
The promotion also says something about how the company has built its bench. Marimaca has run a deliberately small corporate team, which is normal for a developer conserving cash, and the risk in that model is that key knowledge concentrates in a handful of people with no obvious successor. Bringing a vice president of finance through to the chief financial officer seat is the outcome that model is supposed to produce, and it is one that junior mining companies more often fail to achieve, reaching instead for an external hire at precisely the moment internal knowledge matters most.
The wider setting is a copper market in which the shortage is of buildable projects rather than of capital. Copper demand forecasts tied to electrification have attracted substantial investor interest to development-stage names, but the pool of deposits that are permitted, in stable jurisdictions and of a size that fits a mid-tier balance sheet remains small. Chilean oxide projects sit in that narrow band, which is why the financing environment for them has been comparatively open even while equity markets have been difficult elsewhere in junior mining.
Marimaca is listed in both Toronto and Sydney, a dual listing that widens the shareholder base but also means the finance function reports into two regulatory regimes and two sets of market expectations at once. Garner-Winship takes the role with the strategic direction settled and the next test being execution on funding rather than on exploration.