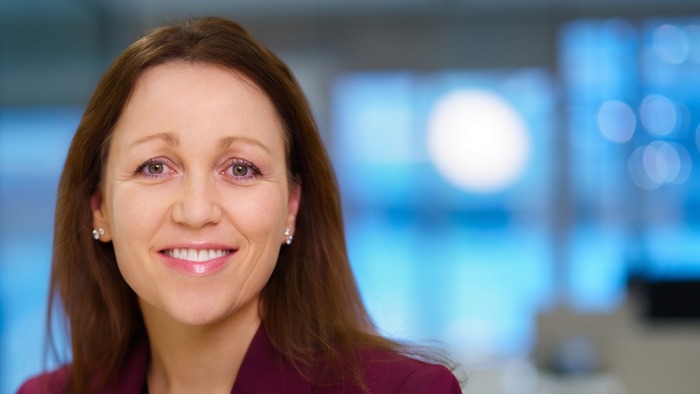
Manulife has appointed Sinead O Connor as Chief Actuary, promoting a nineteen-year veteran of the group to one of the most consequential technical roles in a life insurer and adding her to the executive leadership team.
She succeeds Stephanie Fadous, who died suddenly the previous month. Derek Houle continues as Appointed Actuary until O Connor obtains Canadian accreditation, an arrangement that keeps the statutory role filled while the permanent appointment takes effect.
O Connor joined Manulife in 2007 and has moved through most of the actuarial function. She was most recently Global Head of Inforce Management, the discipline concerned with the economics of policies already on the books rather than with new business, and she has previously served as Deputy Chief Actuary, Head of Group Actuarial and US IFRS Chief Actuary, with earlier roles across annuities, long term care and finance.
That path is unusually well matched to the job. The chief actuary of a life insurer owns the assumptions that determine what the company believes it owes, and in a group of Manulife's shape those assumptions span three very different books: Canadian individual and group business, the United States operations carried under the John Hancock brand, and a fast-growing Asian franchise with a different product mix and a different mortality experience.
Long term care is the part of that record most worth noting. It is the single most assumption-sensitive liability in North American life insurance, where small changes in morbidity, persistency or future care costs compound over decades, and it has produced some of the largest reserve revisions the sector has seen. An executive who has worked inside that book arrives understanding where the uncertainty actually sits.
The inforce management background points at the same thing from the other direction. Insurers have spent recent years extracting value from existing policies through reinsurance, repricing and portfolio transactions rather than through new sales growth, and that work sits at the intersection of actuarial judgement and capital management. A chief actuary drawn from it is positioned to speak to both.
The split between the chief actuary and the appointed actuary is worth explaining, because the two are often conflated. The appointed actuary is a statutory role under Canadian insurance legislation, personally responsible for the valuation of policy liabilities and for reporting on the insurer's financial condition to the board and the regulator. The chief actuary is the executive who runs the function. Holding the two separately while accreditation is completed is the orthodox arrangement rather than a sign of hesitation, and it is the reason the company could name a permanent chief actuary quickly without any gap in its regulatory obligations.
The appointment is internal at a moment when continuity has particular value, and it was made promptly in circumstances that gave the company little notice.