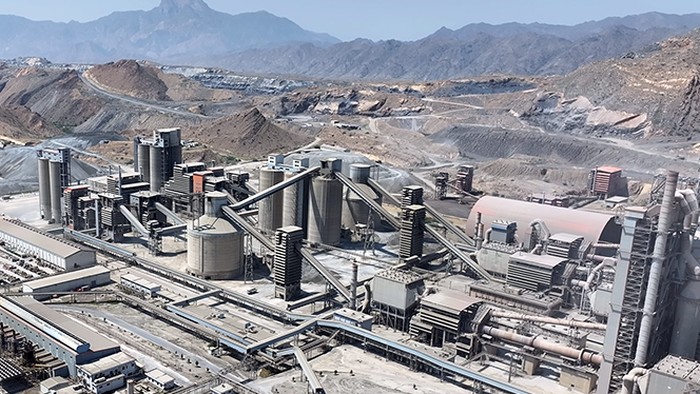
Southern Province Cement Co. told the Saudi Exchange on 16 November 2026 that it has rescheduled a long term Shariah compliant credit facility provided by Saudi National Bank, pushing final repayment out to 2036 from a previous maturity in 2033.
The remaining balance on the facility is SAR 1.44 billion, the company said in its filing. Repayment continues in quarterly instalments across the extended term. The facility is secured by a promissory note, and the cement producer stated that no related parties hold any interest in the arrangement.
The company did not disclose a revised profit margin or any change to the covenants attached to the line. It also did not state a dollar equivalent for the outstanding balance, and figures circulating in regional trade coverage are conversions made by those outlets rather than numbers the issuer published.
Rescheduling rather than refinancing matters for a producer of this kind. Cement manufacturing is among the most capital intensive activities in the Saudi industrial base, with kilns, grinding mills and quarry infrastructure that depreciate over decades. Debt raised against assets of that life sits awkwardly on a repayment schedule built for a shorter horizon, and stretching the final maturity by three years brings the shape of the liability closer to the shape of the asset it funded. The immediate effect is on near term cash: quarterly instalments spread across a longer period are smaller instalments, which releases working capital at a point in the cycle when fuel and clinker input costs have been the sector's principal pressure.
The willingness of the lender to extend is the second signal worth reading. A bank agreeing to carry a facility of this size three years further out is expressing a view about the borrower's cash generation and about the demand outlook for building materials in the kingdom. Saudi cement volumes are tied closely to the construction pipeline, which in turn tracks the giga project programme and the residential build out, both of which run well beyond the original 2033 maturity. A tenor that now reaches 2036 aligns the obligation with the period over which that demand is expected to be realised.
What the filing does not settle is whether the extension carries a repricing. The company disclosed the new maturity, the balance and the security, and left the economics of the rescheduling unstated, so the cost of the additional three years will only become visible in the finance charge reported in subsequent quarterly statements.