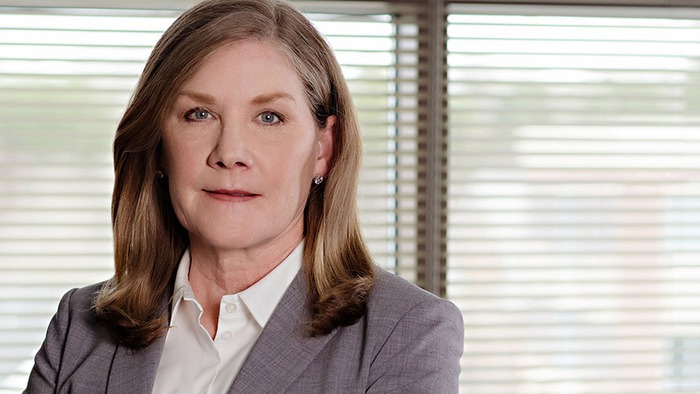
Lynn M. Bamford will become executive chair of Curtiss-Wright Corporation on 1 January 2027, moving out of the chief executive role she has held since 2020 while retaining an executive mandate at board level.
Bamford has spent twenty two years with the defence, commercial nuclear and industrial group, and currently holds both the chair and chief executive titles. She is credited with the company's Pivot to Growth strategy and with a period of record financial performance, including 1.7 billion dollars returned to shareholders. Kevin M. Rayment, the current executive vice president and chief operating officer, becomes president and chief executive officer on the same date and joins the board.
An executive chair, not a retirement
The distinction between chair and executive chair is the whole point of this appointment. A non-executive chair runs the board; an executive chair keeps an operating remit alongside it. For a company that has just posted record results under a named strategy, retaining its author in an executive capacity is a way of holding the plan steady through a chief executive handover rather than putting it up for review.
Robert J. Rivet, lead independent director, made the continuity case in terms of what her tenure produced. "Lynn has transformed our Company through the Pivot to Growth strategy, delivering record financial performance," he said.
Bamford's own framing was about the institution rather than the strategy. "I've enjoyed an amazing 22-year career alongside some of the most talented people in the industry," she said.
What it means for governance
Curtiss-Wright is separating the chief executive and chair roles it had combined, which most governance codes would treat as an improvement. The nuance is that it is separating them into a chief executive and an executive chair rather than into a chief executive and an independent chair, so the board still has an insider in the chair's seat and the lead independent director remains the counterweight.
Whether that is the right structure depends on the end markets. On the company’s own account the recent period has been one of record performance, and the supplier risk in a strong ordering environment is operational rather than strategic: winning the work is easier than delivering it on cost and on schedule. A structure that frees a new chief executive to concentrate on execution while the outgoing one continues to own the growth agenda is a coherent answer to that problem. It is less well suited to a downturn, when the useful thing a chair can do is ask whether the strategy still holds, and an executive chair who wrote it is the least likely person in the room to conclude that it does not.