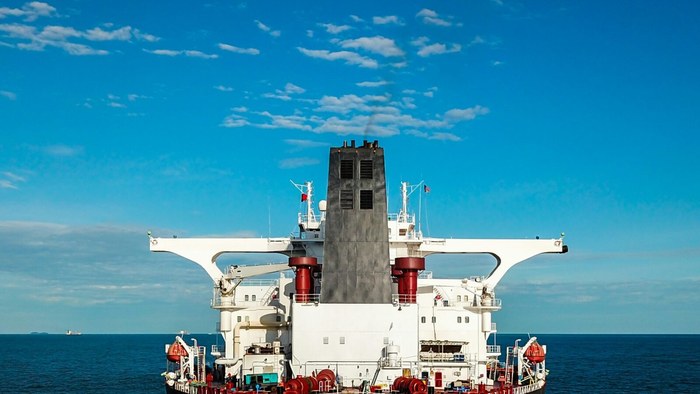
The National Shipping Company of Saudi Arabia, which trades as Bahri, has signed a contract with International Maritime Industries Company for the construction and delivery of three very large crude carriers of 320,000 deadweight tonnes each. The shipowner put the total estimated build cost at approximately SAR 1.692 billion, or about USD 451 million, and recorded both the award and the signature on 22 October 2026. The disclosure reached the Saudi market three days later.
Delivery is planned in batches between 2029 and 2030, and the contract term ends when the final vessel is handed over. Bahri said it will fund the cost from a combination of internal cash resources and banking facilities, and that the financial impact will reach its accounts only as the vessels are received and enter commercial service. With this order, the company put the total number of newbuild vessels now on order in the Kingdom at nine, of which six are dry bulk carriers and three are the crude carriers covered by this contract.
The filing also carries two related party flags, and they are the part a board should read first. Bahri owns 19.9 per cent of the capital of International Maritime Industries Company, and Ahmed Ali Al-Subaey, who is both a board member and chief executive of Bahri, sits on the shipbuilder's board as well. Neither fact is hidden, and disclosing them is exactly what the regime requires. The substantive question is not whether the relationship was declared but whether the price was set as it would have been with an unrelated yard, and that is a question the disclosure does not answer and was never going to. Directors at any listed company placing long dated capital commitments with an affiliate should expect the same question, and should be able to show the benchmark that answers it.
The strategic reading is more straightforward. An order of this size placed with a domestic yard converts a shipping company's fleet renewal budget into industrial capacity inside its own economy, which is the stated intent of the Kingdom's long running localisation programme and the reason such orders attract policy attention as well as commercial attention. For the owner, three tonnage units of this class arriving late in the decade is a replacement and expansion decision taken years ahead of the freight market they will trade into, which is the structural bet every tanker owner has to make and the reason the sector's returns are so cyclical. Readers tracking this should watch the delivery schedule rather than the contract value: a yard still building out its track record carries schedule risk that a mature builder does not, and slippage on a crude carrier is measured in quarters of lost earning capacity. Watch too whether the nine vessel domestic orderbook grows from here, because a second tranche would signal that the localisation route has moved from policy preference to settled procurement practice.