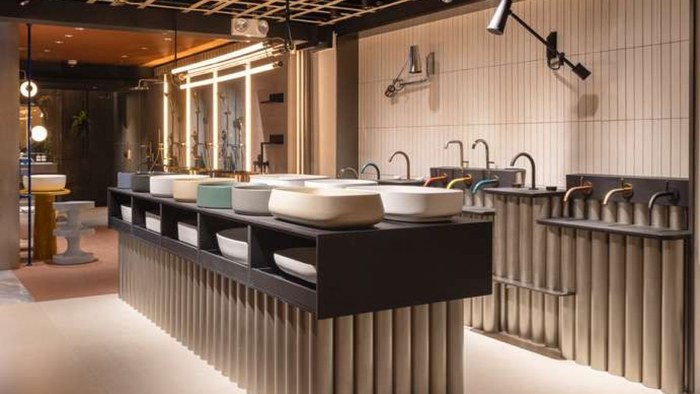
The founding family of Hafary Holdings has launched a voluntary conditional cash offer for the Singapore surfaces and sanitary ware group, at S$0.64 for each offer share. The offer was announced to the Singapore Exchange at the end of September through 23 Capital, a vehicle of the company’s promoters.
The promoters behind the vehicle are Low Kok Ann, Low See Ching and Low Bee Lan Audrey. United Overseas Bank is acting as announcing and financial adviser to the offeror. The offeror has said it does not intend to revise the price except in a competitive situation, and that the price may be reduced by the value of any distribution paid to accepting shareholders.
The decisive figure is the level of pre-commitment. Irrevocable undertakings have been secured over 387,318,540 shares, approximately 89.96 per cent of the company. The offer carries a single substantive condition, the minimum acceptance condition, set at the level of acceptances sufficient to invoke compulsory acquisition under Singapore company law. The announcement states that, save for that condition, the offer will be unconditional in all other respects. Under the Singapore Code on Take-overs and Mergers the offer document follows within two to three weeks of the announcement and must stay open for at least 28 days after it is posted.
A delisting in all but name
With close to 90 per cent of the register already locked up before the offer document has been issued, this is not a contested situation and the outcome is not seriously in doubt. The remaining free float is small enough that the compulsory acquisition threshold is a formality rather than a hurdle, and minority holders are effectively being given a price at which to exit rather than a decision to make.
That shape is becoming familiar on the Singapore Exchange. A steady run of smaller and mid-sized listed companies has been taken private by founding families and controlling shareholders over recent years, and the logic is consistent each time: thin trading volumes, limited analyst coverage and persistent valuation discounts make a public listing expensive in compliance cost and worth little in access to capital. When a family already controls the business and the register, the listing is a liability rather than an asset.
For Hafary specifically, the business is exposed to Singapore construction and renovation activity, which is cyclical and currently constrained by labour and cost pressures. Managing through that cycle is easier without quarterly scrutiny and without a share price that moves on sentiment about a sector rather than on the company’s own performance.
The announcement gives no aggregate transaction value, and none should be inferred: the promoters’ own consideration is being treated as interest-free shareholder loans and is not quantified, so the headline cash outlay is smaller than a simple multiplication of shares by price would suggest.