Slate Grocery REIT has agreed to be acquired by Brixmor Property Group and Everview Partners for 13.00 dollars per unit in cash, a transaction with an enterprise value of approximately 2.3 billion dollars.
The price represents a premium of about 13 per cent to the closing price in late May and about 20 per cent to the close two days before the announcement. Completion is expected in the first quarter of 2027, subject to unitholder approval and court authorisation.
The agreement carries an unusually detailed set of ancillary terms. A management termination payment of 50 million dollars is payable, and the acquisition of the NA Essential joint venture interest runs to approximately 187.5 million dollars. The break fee is approximately 31 million dollars with a reverse termination fee of approximately 63 million dollars, and a daily accrual of 0.002482 dollars per unit applies from late January 2027.
Why grocery-anchored retail keeps attracting capital
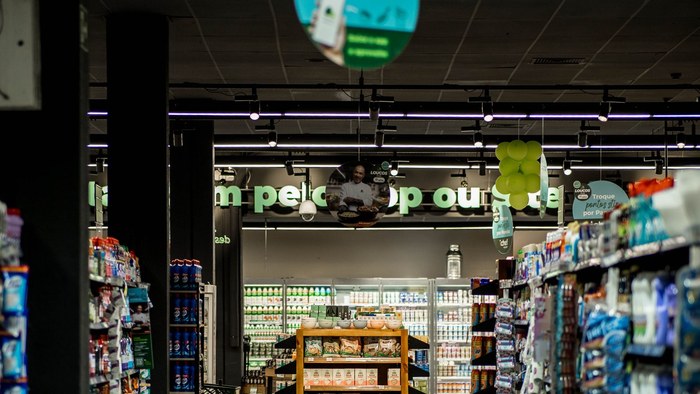
Grocery anchored shopping centres have been the most defensible category in American retail property for most of the past decade, for a straightforward reason. The anchor tenant sells something that cannot be fully displaced by online delivery at current economics, which produces reliable footfall for the smaller units around it. That produces the predictable income streams institutional buyers want.
Brixmor is already one of the largest owners of open air shopping centres in the United States, so this is consolidation within a segment it knows rather than entry into a new one. The presence of a partner alongside it is the more informative detail, and it reflects the scale of equity cheques now required to take a listed vehicle private at this size.
The public to private arithmetic
The premium is the argument. A roughly 20 per cent premium to the recent close is modest by the standards of corporate takeovers but is typical of real estate investment trust buyouts, where the underlying assets are independently valuable and the bidder is paying principally to close a gap between the traded unit price and net asset value.
That gap is the structural reason these transactions keep occurring. Smaller listed property vehicles have traded persistently below the value of their portfolios, which makes them cheaper to buy than the equivalent assets are to assemble. The management termination payment, at 50 million dollars, is a reminder of the other cost that externally managed vehicles carry and that private buyers do not.
Evercore acted as exclusive financial adviser to the special committee, with a fairness opinion from CIBC World Markets. RBC Capital Markets was lead financial adviser to the purchaser, alongside Wells Fargo Securities.
Marc Rouleau chaired the special committee. Blair Welch is chief executive officer and a co-founding partner of the vehicle and its manager.