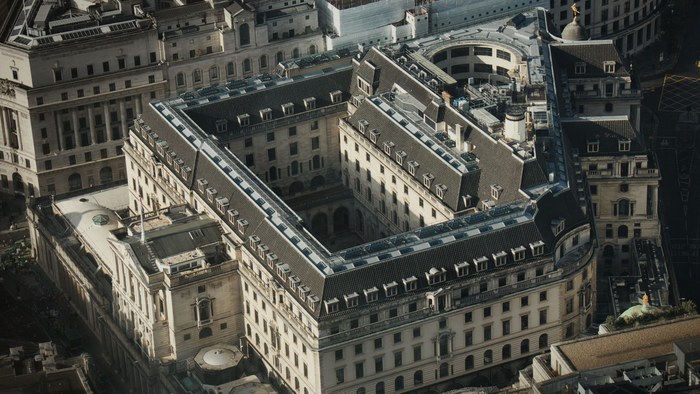
The Bank of England has given its first full account of how quantitative tightening will end, naming the September 2034 gilt as the security whose maturity will complete the unwind of the Asset Purchase Facility. Dave Ramsden, Deputy Governor for Markets and Banking, set out the plan at the Bank on 28 September 2026, in an event co-hosted by the Money, Macro and Finance Society.
The decision the speech explains was taken earlier, by the Monetary Policy Committee at its September meeting and published on 17 September 2026, when Bank Rate was maintained at 3.75 per cent. The Committee was unanimous. "All members agreed at this meeting that the Bank of England should reduce the stock of UK government bond purchases held for monetary policy purposes, and financed by the issuance of central bank reserves, to zero," the minutes record.
The arithmetic is now fixed. Against a peak of 895 billion pounds of asset purchases, the Asset Purchase Facility stock stands at 488 billion pounds, of which 120 billion pounds backs banknotes, leaving 368 billion pounds to unwind. Within that, 222 billion pounds runs off at maturity and 146 billion pounds is sold. "The MPC unanimously agreed that the remaining £368bn of gilts should be unwound at an annual average pace of £46bn by the end of 2034," Ramsden said, "through annual sales of £20bn alongside maturing gilts." The terminal security is named: "The final maturity will be the £28.2bn September 2034 gilt, and the MPC expects that will mark the completion of the QT unwind."
To date the Bank has sold 129 billion pounds of gilts in purchase proceeds across 120 auctions, alongside about 20 billion pounds of corporate bonds. Its balance sheet peaked at 46 per cent of nominal gross domestic product and had fallen to 25 per cent as of June 2026. Since quantitative tightening began in February 2022, 10 year gilt yields rose by around 450 basis points, of which around 200 basis points was driven by term premia. The indemnity from HM Treasury to the Bank remains in place.
The substantive change is the replacement of an annually reset decision with a decade long schedule. Until now the pace of sales was reviewed each September, so gilt investors carried a recurring policy event every autumn. A constant 20 billion pounds a year to 2034, with a named terminal maturity, converts quantitative tightening from a policy variable into a known supply calendar, and duration risk that was previously hard to hedge becomes hedgeable. That should compress the quantitative tightening component of the term premium even if nothing else changes.
For United Kingdom pension and insurance boards that alters the asset allocation question. The largest marginal seller of long gilts has published its runway, which lets liability driven investors and bulk annuity writers plan around a fixed overhang, and the Bank and the UK Debt Management Office now share a visible multi year supply picture. Composition matters too: of the 46 billion pounds a year, only about 20 billion pounds is a live sale.
Two second order effects follow. Because the Treasury indemnity remains, the losses crystallised by selling gilts bought at higher prices stay a fiscal item, and a fixed schedule makes that bill more predictable. And running the facility to zero means bank reserves must eventually be supplied through the Bank's repo facilities rather than through asset holdings, which moves bank treasurers from a passive to an active relationship with the central bank. That is a governance change inside every United Kingdom bank treasury, not merely a market technicality.