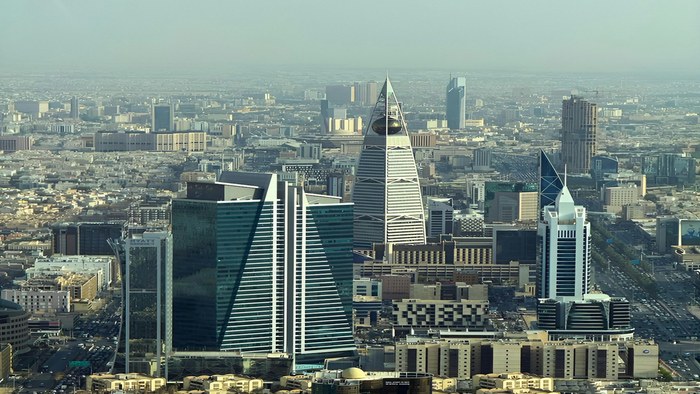
State Street has cleared the last regulatory step standing between it and a working onshore fund services operation in Saudi Arabia. The Capital Market Authority confirmed that State Street Saudi Arabia Financial Solution Company, the group's wholly owned Saudi subsidiary, has completed the commencement of business requirements attached to its licence to manage investments and operate funds in the securities business. The notice was published on 21 October 2026.
The licence itself was granted in June under the Capital Market Law issued by Royal Decree No. (M/30). What changes now is operational rather than legal. A commencement of business confirmation is the regulator's statement that a licensed entity has put the people, systems, capital and controls in place to trade on the permission it already holds. Until that point a licence is an authorisation on paper.
The operating funds half of the permission is the commercially significant one. It allows the subsidiary to provide local fund administration inside the Kingdom, covering fund accounting, financial and regulatory reporting, investment compliance monitoring and tax reporting. Institutional investors, asset managers and asset owners can therefore establish, operate and service funds entirely onshore rather than booking those functions to a centre outside Saudi Arabia. The parent established local operations in the Kingdom in 2020 and later opened a Middle East and North Africa regional headquarters in Riyadh, and says it has served Saudi clients for more than twenty five years.
For chief executives and chief operating officers at Saudi asset managers, insurers and sovereign-linked investment vehicles, this is a supply side change in a market where onshore fund administration has been thin. Boards that accepted an offshore administrator because no credible onshore alternative existed now have a second question to answer at the next service review: whether the operating model should be brought back into the Kingdom, and what that does to data residency, regulatory reporting lines and the cost base. The answer will not be uniform across institutions, but the question is live where it previously was not.
For the market, the sequencing is a signal in itself. Publishing a commencement of business notice separately from the original licence tells readers which authorised firms are actually open. Executives tracking market entry should treat the two notices as distinct events and calibrate accordingly, because a licence tells you who intends to compete and a commencement notice tells you who can. For other global custodians and administrators weighing their own Saudi plans, the practical inference is that the path is demonstrably completable, and that the window in which an onshore administration mandate can be won without an incumbent to displace is narrowing rather than widening.