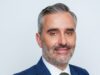
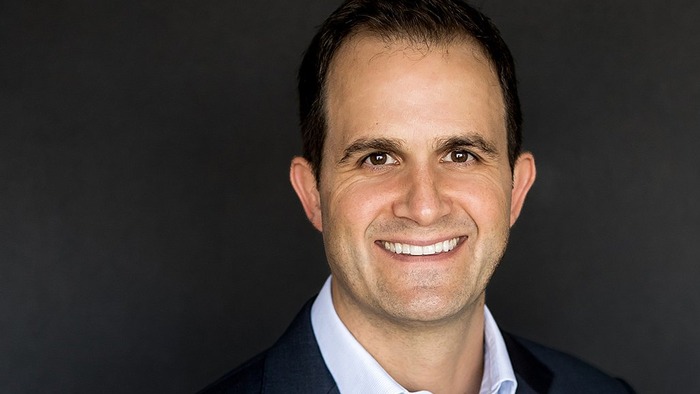
HSBC has appointed Sami Abouzahr as Head of International Wealth and Premier Banking for the UAE and Middle East, effective immediately, in a move that underscores the bank's aggressive expansion into one of the world's fastest-growing wealth markets. Abouzahr, a 20-year veteran of the British lender, relocates to the UAE from Hong Kong, where he served as Head of Investments and Managed Solutions since July 2025. The appointment represents a significant internal promotion within HSBC's wealth division and signals the bank's determination to capture market share in a region attracting a record influx of millionaires and high-net-worth individuals.
Selim Kervanci, HSBC's Chief Executive for the Middle East, North Africa and Turkey, said the appointment reflected Abouzahr's deep expertise in wealth management and his understanding of affluent clients built across Asia and HSBC's international network. Kervanci emphasized that Abouzahr was ideally positioned to capitalize on the significant opportunity in the region as the bank continues investing in people, products and infrastructure. The appointment comes during an acceleration of HSBC's investment in UAE wealth operations, which has been characterized as the bank's largest commitment to the segment in two decades. No external search firm involvement was disclosed in the announcement.
Abouzahr's career trajectory reflects a winding path through HSBC's wealth and asset management divisions. He first joined HSBC in 2005 in corporate and global banking roles, departing in 2008 for a two-year stint at Halbis Capital Management. He rejoined HSBC in 2010 and has since held senior positions including Global Head of Wealth Solutions, Head of Wealth Management in India, and most recently leadership of wealth and premier solutions in Hong Kong. Throughout his tenure, he has developed expertise spanning wealth management, asset management and wholesale banking across operations in Hong Kong, mainland China and the UK, accumulating two decades of international leadership experience.
HSBC has embarked on an unprecedented expansion of its UAE wealth business. In September 2025, the bank opened the Middle East's first dedicated wealth centre at its flagship Jumeirah branch in Dubai, featuring 90 relationship managers serving high-net-worth clients across a 24,000-square-foot facility designed for private meetings and bespoke solutions. A second wealth centre is scheduled for Abu Dhabi by year-end 2026. Concurrently, HSBC doubled frontline staff dedicated to affluent clients, launched an enhanced Premier account, and became the first global asset manager to establish onshore funds in the UAE. Its digital investment platform, World Trader, generated USD 800 million in trading volumes within 12 months of launch. The bank's strategy reflects recognition that the UAE is projected to attract approximately 9,800 new millionaires in 2025, more than any other country globally, according to Henley and Partners wealth migration data.
The Abouzahr appointment reflects HSBC's broader strategic repositioning toward Asia and the Middle East under Group CEO Georges Elhedery. The bank has been scaling back Western operations while directing growth capital toward regions where it holds competitive advantages. HSBC holds that its international network provides unrivalled ability to connect UAE clients to global investment opportunities, particularly in cross-border wealth management, liquidity management and asset allocation across regions. The appointment can be understood as an investment in deepening relationships with increasingly sophisticated, younger, digitally-minded wealth clients showing interest in technology, alternative assets and non-traditional investment vehicles. Whether Abouzahr's appointment signals the bank's confidence in sustained momentum or an attempt to reinvigorate growth in a market where HSBC recently shed 1,000 clients amid regulatory scrutiny remains to be observed in coming quarters.